Daily Issues
The World Beyond the Model Grew
An August 9, 2026 briefing on open-weight licenses, AI power and memory investment, workflow AI results, and US crypto rules and sanctions
Summary
At a glance
- Open-weight models can still require a separate agreement depending on use and business scale, so license review now belongs in deployment cost estimates.
- AI infrastructure bottlenecks extend beyond GPUs to grid connections and the long lead time for new memory capacity.
- The US crypto market-structure bill remains in the legislative process, while sanctions enforcement is already reaching exchanges and related networks.
This market commentary is my record for understanding the news, not a recommendation to buy or sell any asset.
As of the morning of August 9, 2026, Korea Standard Time
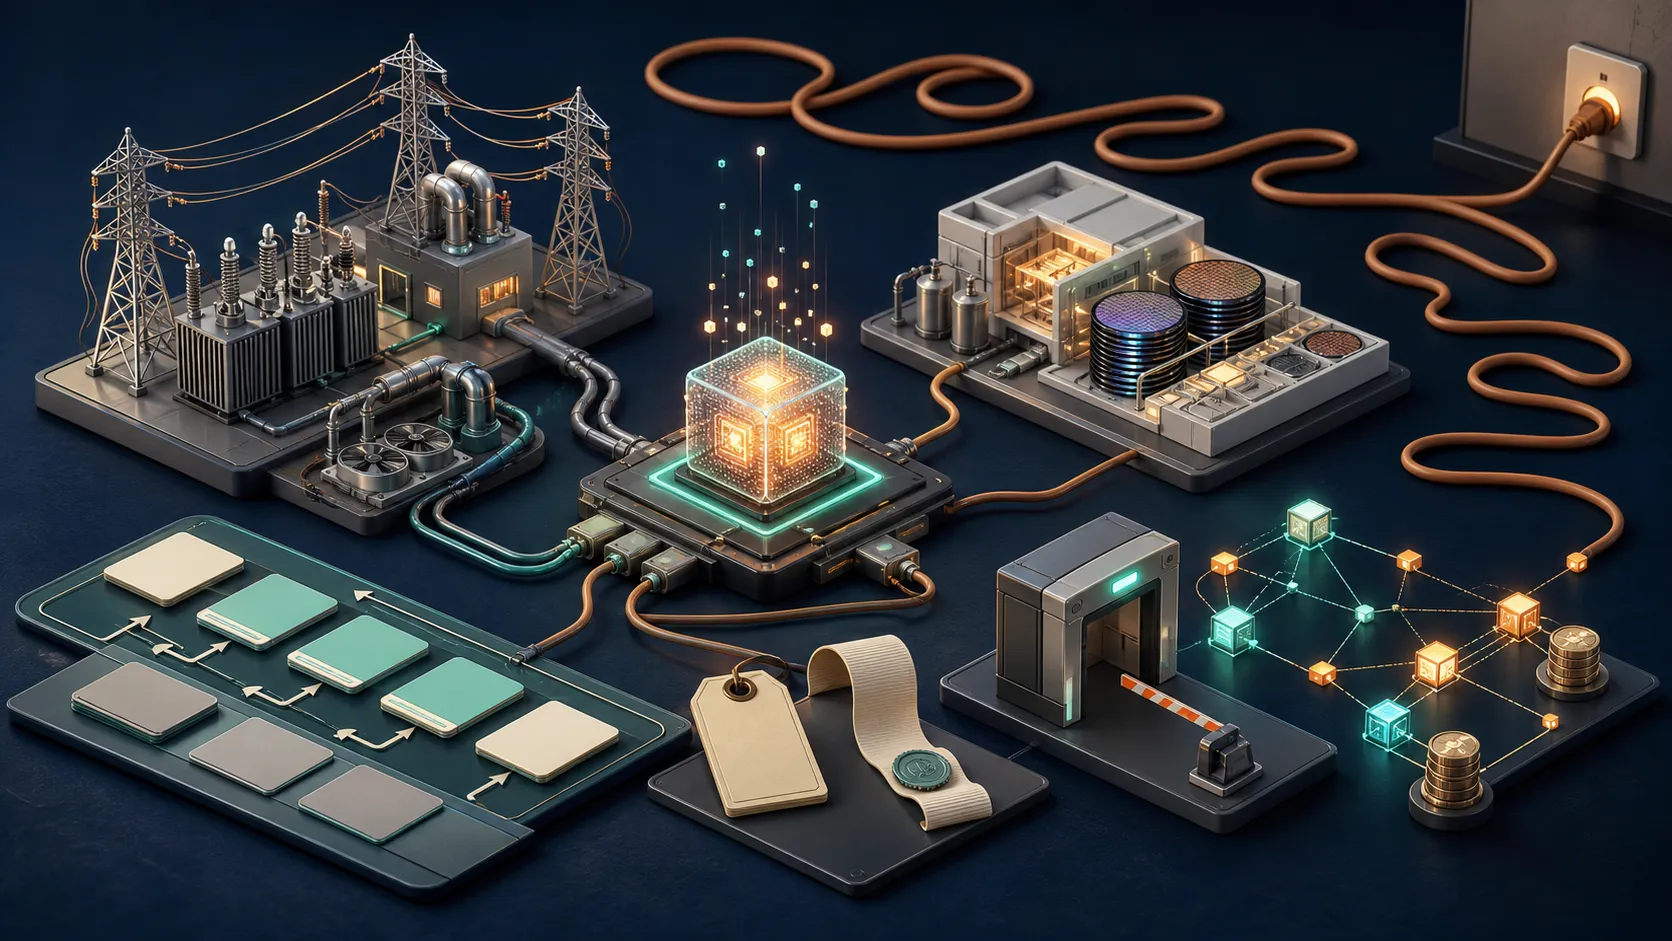
Today, everything around the AI model seemed busier than the model itself. License terms opened up, power and memory projects expanded, and regulators followed crypto transactions. I went looking for a power strip and somehow unfolded an entire industrial map.
I checked the nine supplied items against public source material. I kept the points I could verify and removed claims whose numbers did not match public data or whose original announcement I could not find. The Alibaba and Nvidia items also remain reports rather than final company contract announcements, so I have not treated them as settled deals.
My one-line view
AI cost no longer stops at tokens and GPUs. Licenses, power, memory, workflow data, and compliance are joining the same spreadsheet. The spreadsheet is getting longer, and the AI has not offered to cry over it for me. That feature must be on another plan.
In this revision, the overall picture stays here while the decision process branches into two simpler reads. Investment & Economy: Where the AI Money Went follows capital, results, and risk boundaries. AI Technology: AI Had More Parts follows the deployment path from licensing to permissions. They share evidence, but each answers a different question instead of repeating the same article.
1. Open weights still come with terms
Media reports say Alibaba may ask large commercial users of a future open-weight Qwen model to share revenue. The percentage and final terms have not been settled, and I could not find a published license text. I therefore read this as a business direction under consideration, not a price sheet already in force.
The published Kimi K3 license makes the broader shift easier to see. A business that offers the model itself as a service and earns more than $20 million in aggregate revenue over any consecutive 12 months must reach a separate agreement with Moonshot AI. A commercial product with more than 100 million monthly active users or $20 million in monthly revenue must prominently display the Kimi K3 name. Internal use and access through official or certified partners are exceptions.
The key question is no longer simply whether weights are available. API resale, derivatives, embedded features, and internal use can carry different terms. The download button is the entrance; the license is the checkout. I now want the license version, revenue threshold, and resale clause beside every benchmark score.
Sources: Moonshot AI’s Kimi K3 license, official Kimi K3 repository
2. Power and memory are waiting behind the GPU
A report that Nvidia could invest up to $3 billion in Stargate power-infrastructure developer Lancium drew attention this weekend. What I could verify in company material is the physical foundation: Lancium calls its Abilene, Texas site the flagship Stargate 1 campus and says it has a 1.2GW grid interconnection approved by ERCOT. A GPU without electricity is an exceptionally expensive ornament.
On the memory side, SK hynix’s board approved 35.2 trillion won for Yongin Y2 and 19.1 trillion won for Cheongju M17. The first cleanroom targets are June 2029 for Y2 and December 2028 for M17. Money approved today does not pop out as HBM tomorrow. Construction, equipment, yield stabilization, and customer qualification all take time.
I will therefore stop judging AI capacity by GPU count alone. Grid access, cooling, networking, and the arrival date of memory belong in the same model. The absurdly long cable in today’s cover is a joke. In the industry, it is not much of one.
Sources: Lancium’s Abilene campus, SK hynix’s Y2 and M17 investment announcement
3. Atlassian showed the value of AI inside existing work
Atlassian reported fiscal fourth-quarter revenue of $1.766 billion, up 28% year over year. Cloud revenue reached $1.213 billion, up 31%. The company also said its MCP server and Teamwork Graph CLI passed one million monthly active users.
I do not read this as proof that every chatbot sells. Jira and Confluence already hold work, documents, and permission relationships. AI placed inside that workflow can act without asking users to move into another window. It is like a cook who already knows what is in the fridge. Someone still has to decide who gets the key to the fridge.
For a development team, monthly activity should be the start of measurement, not the end. Completed work, human edits, merge rates, and incidents matter too. Usage is an attendance sheet; outcomes need their own report card.
Source: Atlassian’s official fiscal 2026 fourth-quarter results
4. The CLARITY Act is still near the starting line
The US CLARITY Act aims to define when digital assets are treated as commodities or securities and how the SEC and CFTC divide oversight. It did not become law in August. The Senate’s first procedural vote was pushed into September, with negotiations still unresolved.
That distinction matters. There is a long hallway between “entered the Senate process” and “in force.” Crypto markets sometimes see a light at the end of the hall and applaud as if the elevator has arrived. I plan to keep bills, enacted laws, and implementing rules in separate columns.
Developers should avoid hard-coding one regulatory interpretation today. Token classification, custody, and AML processes should be designed so they can change.
Sources: Congressional Research Service overview of the CLARITY Act, the Senate vote moving into September
5. Legislation waited; sanctions enforcement did not
On August 7, the US Treasury’s OFAC sanctioned Iran-linked digital-asset exchanges and related people, including Shelbit and Aban Tether. Treasury said IRGC-owned addresses sent more than $1 million in digital assets to Shelbit addresses, while more than $2 million moved in the other direction. It said Aban Tether processed millions of dollars in transactions involving several already-designated Iranian exchanges.
The case shows why a transparent blockchain does not make compliance automatic. Matching one address against a list is not enough. Indirect links, new addresses, the 50-percent ownership rule, and exposure to high-risk services require graph analysis and human review. A public ledger is closer to a glass wall than an invisibility cloak. You can see through it; somebody still has to clean it.
Source: US Treasury sanctions on Iran-linked crypto exchanges
My checklist today
- Store the license file and version with every adopted model.
- Add power, cooling, networking, and supply lead times to AI cost models.
- Measure workflow AI by completed quality and human correction, not just users.
- Track crypto bills, laws, implementing rules, and sanctions separately.
- Read the reason for a one-day rally without outsourcing my judgment to it.
My conclusion is simple: as models grow stronger, the contracts, wires, factories, and rules outside them matter more. Before I open the next model leaderboard, I will check the power and the terms. It is less exciting, but it lowers the odds that the eventual invoice knocks me out of my chair.
Every investment decision and its outcome remain the investor’s responsibility.
Leaving a reaction may store a random identifier in this browser to prevent duplicates.